
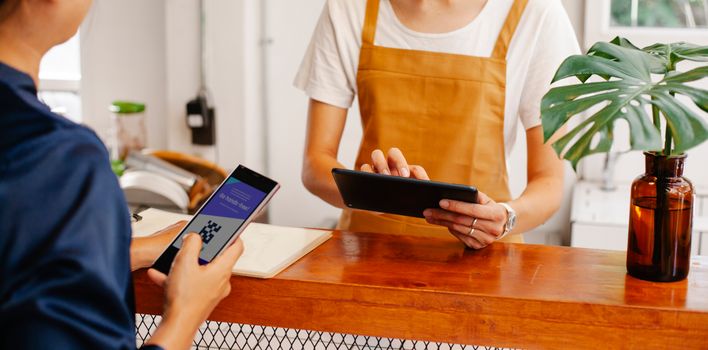
The National Payments Corporation of India (NPCI) released a detailed FAQ on September 15, 2026, explaining its revised Merchant Discount Rate (MDR) framework for select UPI Person-to-Merchant (P2M) transactions, which takes effect from October 15, 2026. Under the new rules, P2M UPI transactions above ₹2,000 will attract an MDR of 0.4%, while consumers continue to pay no transaction fees on any UPI payment.
The MDR framework marks the reintroduction of merchant-side charges on larger UPI transactions after years of a zero-MDR regime that supported UPI’s rapid adoption across India. The charge structure caps fees at ₹300 for transactions above ₹75,000, while payments in categories such as railways, telecom, insurance, and fuel will attract a flat ₹5 fee regardless of transaction size.
Who Pays the New UPI Merchant Fee?
The MDR is levied on merchants, not consumers, meaning UPI remains free for any individual making a payment. Small merchants, including street vendors and local shops processing up to ₹1 lakh per month via QR code in the P2M category, are fully exempted from the new charges, insulating India’s vast base of micro-merchants from the fee while larger merchants absorb the cost on higher-value transactions above ₹2,000.
What Do Payment Industry Players Say?
The proposal has drawn political pushback ahead of its October rollout, with critics arguing that reintroducing merchant fees could dent UPI’s appeal for larger retailers even as small merchants remain protected. Payment aggregators and fintech platforms have been given a one-month window between the September 15 FAQ release and the October 15 effective date to implement the operational changes needed to calculate and collect the tiered MDR structure across their merchant networks.
Market and Trade Reaction
Banks and payment service providers are expected to be the primary beneficiaries of the MDR, as the fee revenue flows to the ecosystem participants who have long argued that a zero-MDR regime made UPI infrastructure economically unsustainable at scale. Larger retailers and e-commerce platforms processing high transaction volumes above ₹2,000 will see the most direct cost impact, while P2P transfers between individuals remain completely unaffected and fee-free.
What Happens Next?
Banks, payment aggregators, and fintech platforms have until October 15, 2026 to complete the operational rollout of the new MDR structure. NPCI and the government will likely monitor merchant and consumer response in the weeks following implementation, particularly given the political pushback already surfacing, and further clarifications or adjustments to the fee slabs cannot be ruled out before or shortly after the effective date.
Frequently Asked Questions
When does the new UPI merchant fee take effect?
The revised MDR framework takes effect from October 15, 2026, following NPCI’s detailed FAQ released on September 15, 2026 explaining the fee structure.
How much is the UPI merchant fee?
P2M UPI transactions above ₹2,000 will attract a 0.4% MDR, capped at ₹300 for transactions above ₹75,000, while railways, telecom, insurance, and fuel payments attract a flat ₹5 fee.
Do consumers have to pay the new UPI charges?
No. Consumers continue to use UPI free of charge for all transactions. The MDR is paid by merchants, and small merchants processing up to ₹1 lakh per month via QR code are fully exempted.


Leave a comment