
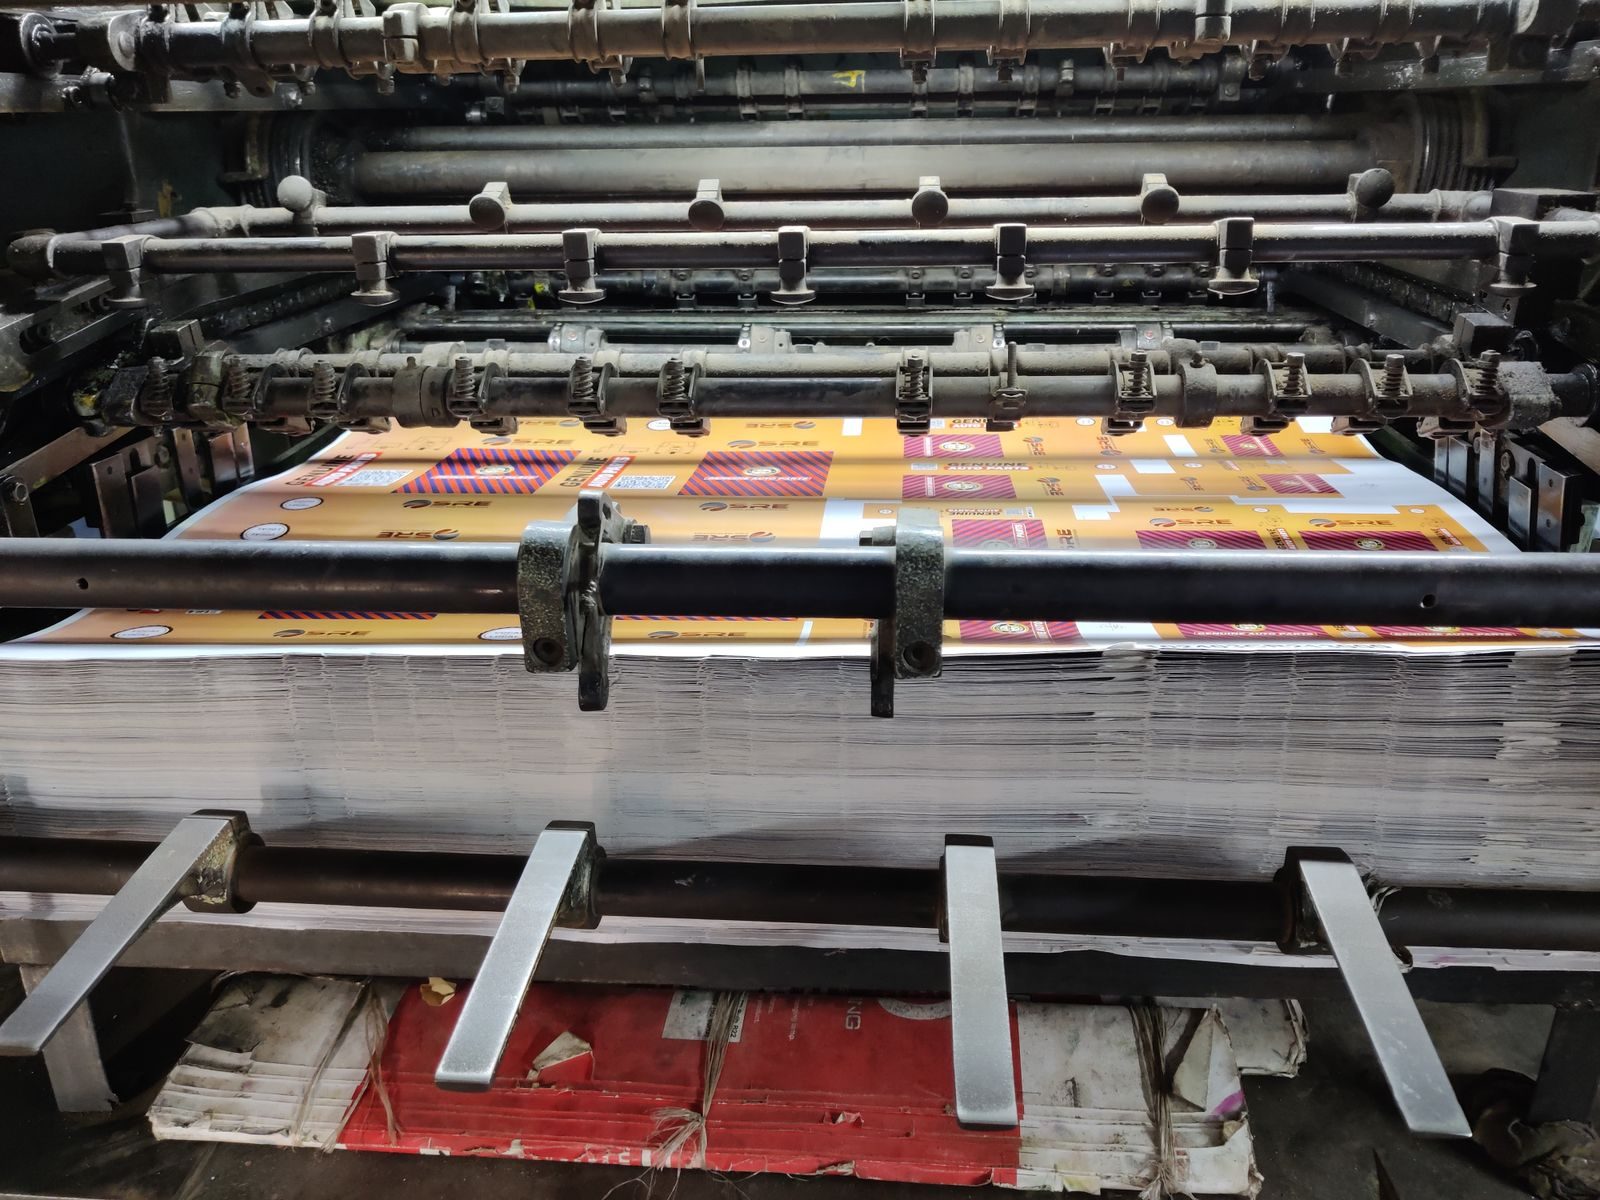
GST refund rules that affect printing and packaging companies were the subject of a seminar held by the Offset Printers Association (OPA) in Ludhiana, Packaging South Asia reported on 19 November 2026. The session covered recent amendments to refund provisions, and the revised refund application form, GST RFD-01, applies from 1 December 2026.
The association called the meeting because delayed GST refunds and accumulated Input Tax Credit (ITC) are tying up working capital for its members.
What Has Changed in the GST Refund Rules?
Advocate Karan Chawla, a Ludhiana-based taxation law professional, was the special expert. The changes discussed were introduced through Central Tax Notifications No. 03/2026 and 05/2026. According to the report, the main points were:
The 90% provisional refund facility has been extended to eligible inverted duty structure cases, subject to risk-based assessment. Eligible input services are now included in Net ITC for inverted duty structure refunds. The 1.5-times restriction on the value of zero-rated supplies has been removed. Provisions to include eligible ITC on capital goods in refund calculations are forthcoming.
Why This Matters for Printing and Packaging Units
An inverted duty structure arises when the tax paid on inputs is higher than the tax charged on the finished product, leaving credit stuck with the manufacturer. For members facing this, a provisional refund of 90% and a wider definition of Net ITC bear directly on how much cash is released and how soon.
Members raised questions on eligibility, pending claims, documentation and dealings with GST authorities, which Chawla addressed.
Market Reaction and Industry Response
Parveen Aggarwal of OPA welcomed attendees. Kushl Kumar Jain (senior vice president), Gagandeep Singh (vice president) and Hans Raj Chopra (finance secretary) of OPA felicitated Chawla. The report carried no direct quotes, and no figure for the amount of refunds pending with members was given.
What Happens Next?
The revised GST RFD-01 refund application form applies from 1 December 2026. The provisions on capital-goods ITC were described as forthcoming, with no date given. Units with pending claims should check the notifications with their own tax advisers, as this article is a news summary and not tax advice.
Frequently Asked Questions
When does the revised GST RFD-01 form apply?
From 1 December 2026, according to the seminar report.
Which notifications introduced the changes?
Central Tax Notifications No. 03/2026 and 05/2026.
Who organised the seminar?
The Offset Printers Association (OPA) held it in Ludhiana for printing and packaging industry members, with Advocate Karan Chawla as the expert speaker.
Source: Packaging South Asia, 19 November 2026.


Leave a comment